Investor Letters
Oct newsletter
A month ago, India was the market nobody wanted to touch. Today, looks like FIIs can’t get back in fast enough. Funny how quickly the story changes.
We are seeing a possible regime shift over the last week or two. The narrative for FIIs seems to have flipped from ‘Anywhere but India’ to ‘India, the safe haven’. Too early to say if it sustains, but it is a welcome change.
Let me walk you through three signs that the tide may finally be turning our way, and one global risk staring at all of us.
One: The FIIs are coming back
₹60,698 Cr. That is what FPIs have bought in Indian equities in just seven trading days of November. The highest net buying over any seven consecutive trading days since January 2021.
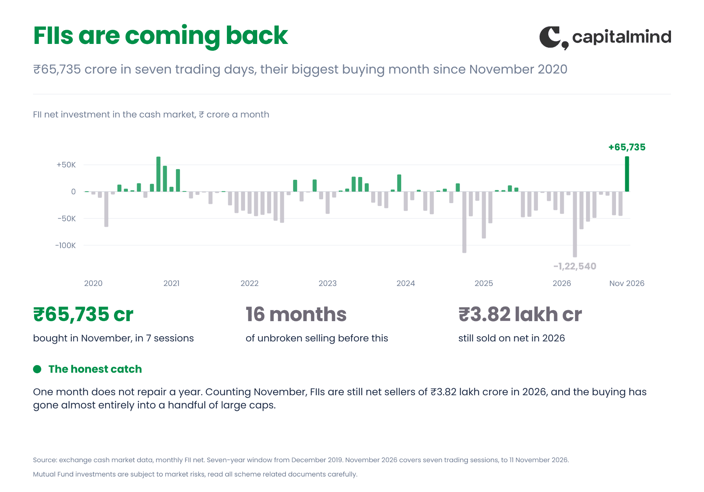
Where did the money go? To the large caps, of course. Nifty 50 is up ~14.5% from the October lows, with a similar move in Bank Nifty. But this is still a narrow move, restricted to a handful of names like Reliance, HDFC Bank, ICICI, Axis, SBI etc. The broader market hasn’t participated yet. Over the last month, Nifty 50 and Nifty Bank were up 12.8% and 11.5%. Nifty Midcap 100 and Smallcap 250? Just 5.2% and 1.1%.
If the FIIs are really back and these inflows sustain, it is only a matter of time before the money finds its way to mid and smallcaps too. Let’s see.
Two: The earnings are strong
Q2 is almost done, and it turned out far better than anyone expected. Remember the backdrop we walked into Q2 with, crude above $100, geopolitical tension, sea routes and logistics disrupted. And still, India Inc delivered.
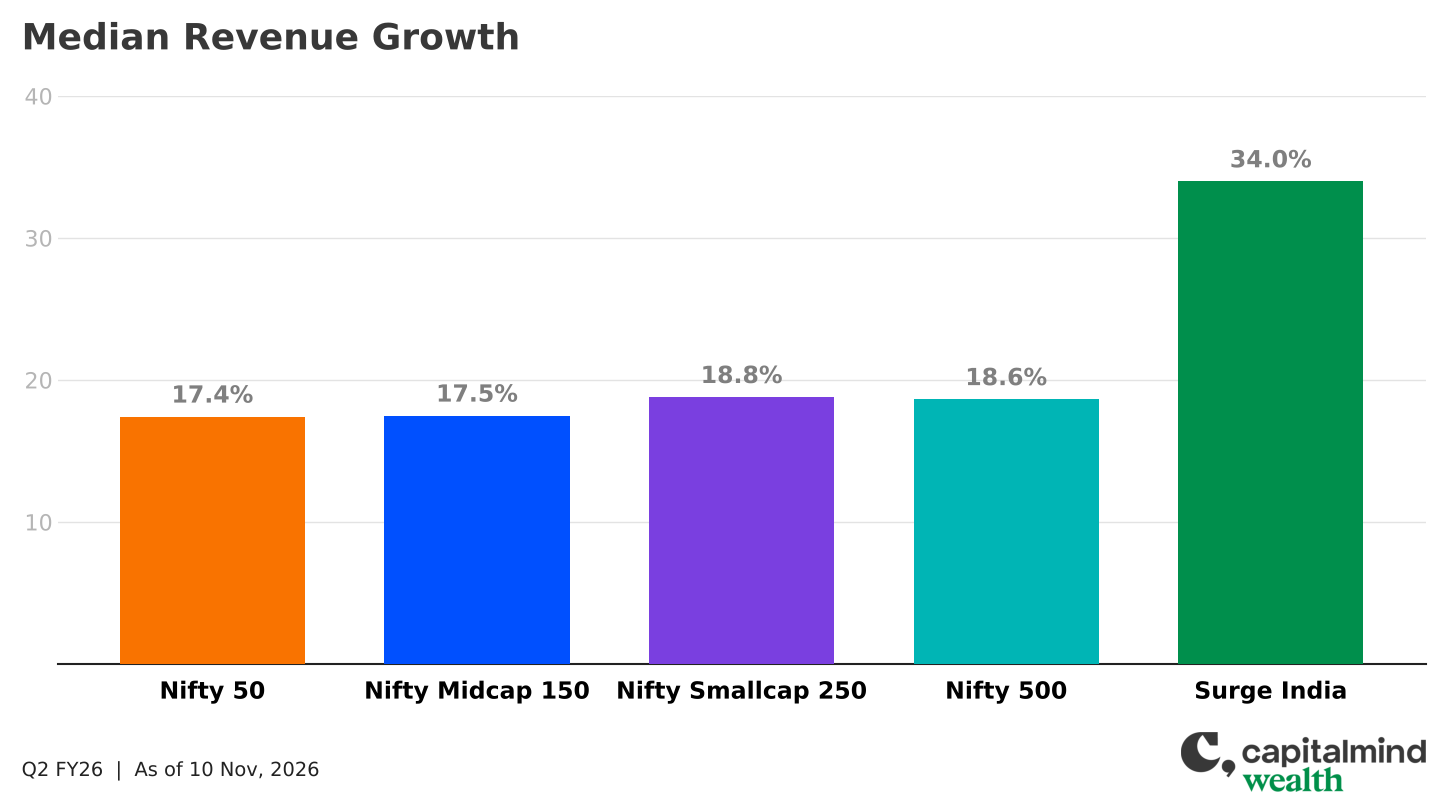
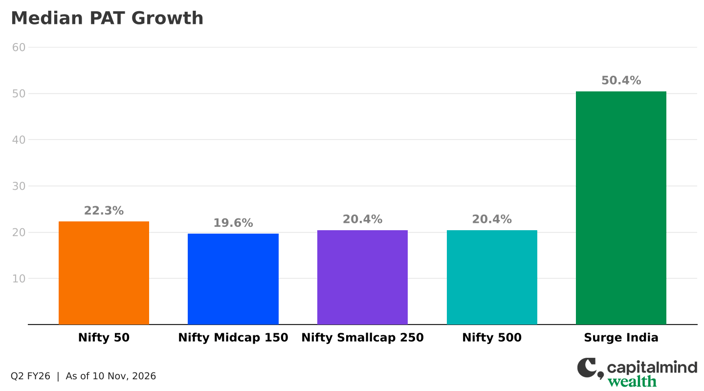
The median revenue growth for Nifty 50 and NSE 500 stands at 17.4% and 18.6%. Median PAT at 22.3% and 20.4%, as of Nov 10th. Numbers like these, in a quarter like that, tell you something about the quality of these businesses.
Three: The valuations are right
The market went nowhere while earnings kept doing their job, and the result is a market that looks reasonable even after this run-up. Nifty 50 is at a one-year forward PE of around 18x (5Y median 20.8x), Nifty Midcap 150 around 25x (5Y median 30x), Nifty Smallcap 250 at 29x (5Y median 28.3x). Broadly, nothing stretched. There is no euphoria out there. If anything, there is still a fair bit of despair.
Put all three together, the liquidity is coming back, earnings are at a two-year high, and valuations are still sane, and this is the best setup we have seen in two years.
And now, the one risk: AI
I can’t write this note without talking about the elephant in the room. The global AI trade, which has carried markets for years, is starting to wobble, and that is worth paying attention to.
The questions have changed. Investors have moved from asking ‘how big is the next capex?’ to ‘when do we actually see the ROI?’. That shift matters. AI is here to stay, no denial there. But patient capital is slowly losing its patience with AI. That is the whole point.
Look at the signals. When OpenAI sets out to raise $30B at a $1.4T valuation and ends up closing its first tranche at $1.25T, well short of the ask, something is clearly shifting. Across the AI ecosystem, the focus has quietly moved from chasing P&L growth to shoring up the balance sheet. You can’t ignore that.
Coming to our strategies.
Surge India
Surge India was down -4.1% in Oct 2026, as compared to our primary benchmark Nifty 50 TRI at +1.9% and secondary benchmark Nifty 500 Multicap 50:25:25 TRI at -1.8%.
Surge delivered a strong Q2. The median revenue growth is at 34% YoY, and median PAT growth is at 50.4% (as of Nov 10th).
On the holdings front, we are reducing our allocation to Indian AI ancillary companies.
As discussed above, for about 3 to 4 years, the entire ecosystem had a dream run: the hyperscalers, chip makers, memory players, ancillaries, both globally and here at home. It was a clean, one-way trade. We participated, and we benefited.
For the first time, it may not be that straightforward anymore. For Indian AI ancillaries specifically, the real risk is PE derating. A theme that is well discovered, with most names trading at 70-100 times earnings, leverage building in the AI ecosystem, and now some uncertainty creeping in. That combination leaves very little room for error.
As we speak, we have other names offering us the same kind of growth, at a better starting valuation and a far better risk-reward. So for now, we are out of the AI trade in Surge. I am not saying AI is a bubble. Honestly, I don’t know. All I am saying is that today, we have other places to be where the risk is lower, and the opportunity is just as good.
We can be spectacularly wrong on this. We have been many times before. But that is ok. The whole game is finding the balance between risk and reward, and adjusting as new information comes in.
Our top 3 sectors continue to be Automobiles & Components (21.7%), Capital Goods (20.5%) and Pharmaceuticals (19.7%), and we remain bullish on all three.
Surge India completed 9 years this month. We will host a webinar in the first half of December (tentatively) to walk you through the performance, our view on the markets, and how we are positioned. You will receive the invite shortly.
Adaptive Momentum
Adaptive Momentum was down -2.6% in Oct 2026, as compared to our primary benchmark Nifty 50 TRI at +1.9% and secondary benchmark Nifty 500 Multicap 50:25:25 TRI at -1.8%.
Since the revamp in May 2026, the strategy has done pretty well. It captured the upside with noticeably lower volatility than momentum indices like the Nifty 200 Momentum 30 (for reference only, not our benchmark). It has shown resilience in the volatile stretches and good strength when the market found momentum. It is still only 6 months, so we hold our enthusiasm in check. But if the broader market keeps trending up on the back of strong flows, we are confident this can continue.
To summarise,
After two years of waiting, three things have finally turned our way at the same time: liquidity is coming back, earnings are strong, and the valuations are still sane. None of them alone means much. Together, they are the best setup we have seen in two years.
Yes, there is a global risk flashing in the background, and we are watching it closely. But you never get a clean setup with zero risk, those don’t exist. You get moments where the odds quietly turn in your favour, and this feels like one of them.
Till next time,
Krishna Appala